

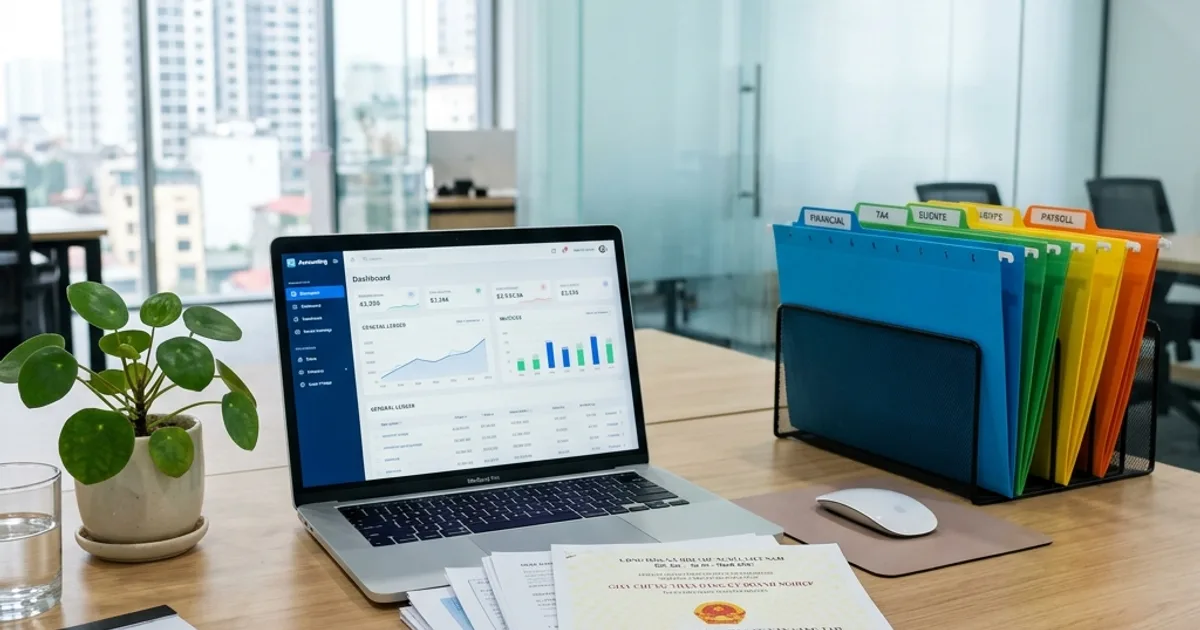


Establishing an initial accounting and financial reporting system represents a foundational milestone for foreign-invested enterprises (FDIs) entering the Vietnamese market. Far beyond configuring standard bookkeeping software or recording initial administrative expenses, an FDI accounting architecture must function as an integrated compliance engine harmonizing Vietnamese accounting standards, dynamic tax obligations, and strict foreign exchange control regulations.
For multinational investors, substantive divergence between Vietnamese Accounting Standards (VAS/VACS) and International Financial Reporting Standards (IFRS) frequently introduces costly operational traps if not architected correctly from day one. Under the modernized mandate of Circular 99/2025/TT-BTC and rigorous electronic invoicing enforcement, establishing compliant accounting infrastructure from licensing is an absolute prerequisite to secure corporate expense deductibility, pass independent statutory audits, and guarantee unimpeded cross-border profit remittances.
1. Legal Framework and Accounting Regime Selection for FDI Entities
The corporate accounting regime in Vietnam operates under the Law on Accounting No. 88/2015/QH13, Government Decree No. 174/2016/ND-CP, and circulars issued by the Ministry of Finance regulating enterprise accounting standards.
For newly established FDI entities, the first critical governance decision involves selecting the appropriate accounting regime during initial tax registration:
- Circular 99/2025/TT-BTC (Comprehensive Enterprise Accounting System): Effective from January 1, 2026, for financial years beginning on or after this benchmark date, replacing Circular 200/2014/TT-BTC. Circular 99 applies universally to all enterprises across all economic sectors, providing an exhaustive chart of accounts, detailed accounting controls, and specialized treatment for modern asset classes such as Biological Assets (Account 215) and Global Minimum Tax top-up obligations (Account 82112). The selected regime must be applied consistently across the entire fiscal period.
- Circular 133/2016/TT-BTC (Simplified Accounting System for SMEs): Applicable to enterprises meeting statutory criteria for small and medium-sized enterprises under SME development laws, offering a condensed ledger and simplified financial reporting schedules.
While micro and small FDI entities possess the statutory option to register under Circular 133/2016/TT-BTC, advisory practice demonstrates that over 90% of foreign entities, particularly manufacturing plants, export processing entities, and subsidiaries with related-party transactions, deliberately register under Circular 99/2025/TT-BTC. Adopting Circular 99 avoids onerous database reconfiguration costs during commercial scaling and streamlines conversion worksheets required for group IFRS consolidation.
2. Accounting Organization and Chief Accountant Appointment Rules
Organizing the corporate accounting function is a strictly regulated mandate under the Law on Accounting and Decree 174/2016/ND-CP, directly engaging the legal liability of the enterprise legal representative.
Pursuant to Article 20 of Government Decree No. 174/2016/ND-CP, the appointment of key accounting personnel for newly established entities adheres to strict statutory principles:
- The 12-Month Grace Period: Newly incorporated enterprises unable to appoint an immediate Chief Accountant are legally permitted to appoint a “Person in Charge of Accounting” (Người phụ trách kế toán) or retain a licensed accounting service practice to provide chief accountant services. The statutory duration for retaining a Person in Charge of Accounting cannot exceed 12 months from the date of issuance of the Enterprise Registration Certificate (ERC).
- Mandatory Formal Appointment: Upon the expiry of the 12-month window, the enterprise must execute a formal appointment decision for a qualified Chief Accountant possessing the requisite Ministry of Finance certificate under Article 54 of the Law on Accounting, professional accounting qualifications, and documented practical experience of at least 2 to 3 years.
- Zero Personnel Vacancy: An enterprise cannot leave the accounting leadership position vacant. Immediately upon incorporation, the legal representative must register the designated Person in Charge of Accounting or Chief Accountant with the local tax department to activate direct investment capital bank accounts (DICA), obtain digital signatures, and register statutory e-invoices.
Retaining licensed outsourced chief accountant services during the initial operational phase enables foreign enterprises to maintain continuous accounting oversight while ensuring compliance during state tax audits.
3. Chart of Accounts Configuration and ERP Software Integration
A pervasive technical challenge for multinational corporations operating in Vietnam is resolving the operational conflict between corporate global charts of accounts and the standardized Vietnamese Chart of Accounts enforced by local legislation.
Vietnamese accounting law strictly mandates that statutory accounting records be maintained in Vietnamese (or bilingual Vietnamese and English) utilizing the standardized account numbering scheme prescribed by the Ministry of Finance:
- Class 1 and 2 Accounts (Assets): Manage cash funds, direct investment capital bank accounts (DICA), current operating accounts, accounts receivable, and inventory categories. Segregation between capital accounts and commercial operational accounts is mandatory, and accounting records must be archived for a minimum statutory period of 10 years under Article 41 of the Law on Accounting.
- Class 3 and 4 Accounts (Liabilities and Equity): Account for vendor trade payables, short-term and medium-long-term foreign shareholder loans (requiring State Bank of Vietnam registration if tenor exceeds 1 year), and charter capital contributions specified on the IRC.
- Class 5, 6, 7, 8, and 9 Accounts (Revenues and Expenses): Record commercial operating income, direct cost of sales, selling and administrative expenses, financial charges, and net profit determination recorded across General Journals and General Ledgers.
When deploying enterprise resource planning (ERP) platforms such as SAP, Oracle NetSuite, or Microsoft Dynamics, foreign enterprises must establish an automated Chart of Accounts Mapping Matrix. Configuring bidirectional mapping rules from the outset allows the system to generate General Ledgers and Trial Balances compliant with VAS statutory requirements without distorting corporate IFRS headquarters reporting.
4. Daily Bookkeeping, E-Invoice Compliance, and Tax Deductibility Requirements
Daily accounting transactions in Vietnam are governed by strict documentary substantiation requirements. Business expenditures, even when substantiated by valid commercial contracts and authentic bank debit advices, will be systematically disallowed during tax audits if statutory documentation standards are breached.
FDI enterprises must enforce 3 primary evidentiary criteria:
- State-Verified Electronic Invoices: In compliance with Decree 123/2020/ND-CP and Circular 78/2021/TT-BTC, transitioning to Decree 254/2026/ND-CP and Circular 91/2026/TT-BTC, inbound purchase invoices must carry authorized tax authority verification codes or certified data transfer logs. The buyer legal name, tax code, and address must match the ERC registration with 100% precision. For imported goods, customs clearance declarations form a mandatory prerequisite.
- Mandatory Non-Cash Payment Documentation: Under the Law on Corporate Income Tax (Law 67/2025/QH15) and Law on Value-Added Tax (Law 48/2024/QH15 effective July 1, 2025), purchase transactions must be settled strictly via commercial bank wire transfers with bank payment confirmation vouchers. Specifically, non-cash settlement is mandatory for transactions of VND 20 million or more for CIT deductible expenses, and VND 5 million or more for input VAT credits. Cash settlements exceeding these statutory thresholds trigger automatic forfeiture of VAT input credits and CIT expense deductibility.
- Intercompany Shareholder Charges: Cross-border management allocations, technical service fees, royalties, and expatriate salary recharges from overseas corporate affiliates require formal contracts, granular timesheets, demonstrable commercial benefit deliverable logs, Foreign Contractor Tax (FCT) filings, and strict adherence to the 30% EBITDA net interest cap under Decree 132/2020/ND-CP (as amended by Decree 20/2025/ND-CP and Decree 255/2026/ND-CP).
Conducting real-time automated verification of incoming vendor e-invoices against the General Department of Taxation national database serves as a vital internal control against fraudulent or suspended vendor invoices.
5. Year-End Book Closing and 4 Mandatory Financial Statement Components
Year-end closing procedures require rigorous coordination between corporate financial leadership and executive management to review year-end expense accruals, inventory net realizable value provisions, bad debt allowances, and fixed asset depreciation schedules pursuant to Circular 45/2013/TT-BTC, aligned with comprehensive physical inventory stocktaking on December 31.
Under Circular 99/2025/TT-BTC, an annual statutory financial statement package in Vietnam comprises 4 mandatory components:
- Statement of Financial Position (Balance Sheet): Summarizes the comprehensive structure of short-term and long-term corporate assets, liabilities, and total shareholder equity at the close of the financial year.
- Statement of Comprehensive Income (Income Statement): Details net sales, cost of goods sold, financial income and expenses, selling and general administrative expenses, and corporate operating income before and after CIT.
- Statement of Cash Flows: Tracks gross cash inflows and outflows categorized across operating, investing, and financing activities during the reporting period.
- Notes to the Financial Statements: Discloses essential qualitative information, specific accounting policies, asset movement schedules, loan terms, related-party disclosures, and non-adjusting post-balance sheet events.
For foreign-invested subsidiaries, the Notes to the Financial Statements receive the closest inspection from independent auditors and tax inspectors to evaluate transfer pricing substance and arm’s-length compliance.
6. 90-Day Statutory Audit Process and Profit Repatriation Blocking Risks
Unlike domestic private enterprises, all foreign-invested enterprises in Vietnam are subject to compulsory annual statutory audits under Law on Independent Audit No. 67/2011/QH12 and Government Decree No. 17/2012/ND-CP.
Pursuant to the Law on Accounting, the statutory deadline to complete the statutory audit and submit financial reports is 90 days following the end of the fiscal year (March 31 for calendar-year entities). Audited financial statements must be simultaneously submitted to 3 regulatory authorities:
- The supervising Tax Office via the eTax electronic portal alongside the annual CIT finalization dossier.
- The Investment Registration Authority (Department of Finance or Industrial Zone Management Board) via the National Foreign Investment Information System (fdi.gov.vn).
- The provincial Statistics Department in the municipality where the headquarters is domiciled under the Law on Statistics.
Submitting late or failing to conduct statutory audits triggers administrative cash penalties ranging from VND 10 million to VND 50 million under Decree 41/2018/ND-CP. Crucially, under Ministry of Finance Circular 186/2010/TT-BTC, commercial remitting banks are legally barred from executing outbound dividend transfers if the enterprise has not submitted fully audited financial statements bearing unmodified opinions or continues to carry unabsorbed cumulative tax losses. Disciplined initial accounting setup represents the ultimate legal safeguard for foreign capital returns in Vietnam.